What Changed and Why It Matters
World models are leaving the lab and entering the built world. Think digital twins that plan, simulate, and act. The goal is simple: higher utilization and fewer bad decisions.
Data centers, grids, and construction face hard limits. Power, water, materials, and labor. The sector now needs AI that can reason about the physical world, not just text.
“Explore how world models could shape the next generation of AI by enabling deeper reasoning, planning, simulation, and real-world …”
This shift aligns with the “AI infrastructure” era. Capital is flooding into compute, energy, and land. But constraints are biting.
“The AI gold rush is meeting a harsh reality: our physical grid and local resources can’t keep up.”
Here’s the part most people miss. The moat won’t only be bigger models. It will be accurate world models tied to real assets, with utilization baked into the P&L.
The Actual Move
Ecosystem players are converging on a playbook: apply world-model-style AI to infrastructure operations.
- Built-world AI is broadening beyond analytics. Robotics on sites. Computer vision in QA. Generative systems in building automation.
“AI for the built world encompasses anything from robotics used in construction, to computer vision and generative AI to create smart buildings …”
- Construction is a prime early adopter. Traditional software hit limits in chaotic, physical workflows. AI is stepping in.
“Yet traditional software is likely not to be enough. If anything, AI is poised to play a critical role in the transformation of the construction …”
- Investors are reframing valuation. Infra plays optimize for utilization, scalability economics, and durable moats.
“Infrastructure plays require different valuation models than software – focusing on utilization rates, scalability economics, and moat …”
- The buildout is not zero-sum. Multiple layers win: power, chips, networking, cooling, storage, and specialized software.
“This week’s earnings season delivered a clear message — the AI infrastructure buildout is not a zero-sum game, and the capital being …”
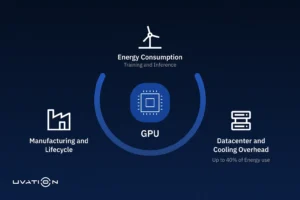
- But the physical world is the bottleneck. Power and water shape siting, scaling, and model deployment.
“The AI gold rush is meeting a harsh reality: our physical grid and local resources can’t keep up. From staggering power needs and water …”
- For developing countries, policy and capacity determine participation. Real-time attention is flowing to infrastructure, funding, and jobs.
“Real-time AI news with analysis for developing countries: policy, infrastructure, models, funding and jobs, updated around the clock …”
Zoom out and the pattern becomes obvious: world models plus digital twins are the control layer for the AI infrastructure era.
The Why Behind the Move
Builders are matching model capability with asset realities.
• Model
World models learn structured representations of environments. They support prediction, planning, and counterfactuals. That is exactly what grid operators, data centers, and construction managers need.
• Traction
Built-world AI already saves time and reduces rework. Robotics and computer vision automate error detection. Generative control systems optimize HVAC and space usage. World models amplify those wins by simulating before acting.
• Valuation / Funding
Utilization is the KPI. Infra investors price assets on throughput, uptime, and marginal economics. Software that boosts utilization or defers capex reshapes asset value.
• Distribution
Distribution follows integrators and asset owners: EPCs, REITs, utilities, hyperscalers, facility managers. The winning go-to-market is embedded into existing control stacks and SLAs.
• Partnerships & Ecosystem Fit
Expect tight ties with utilities, chip vendors, energy developers, and regulators. Data-sharing and validation pipelines become moats. Safety and compliance are product features.
• Timing
Compute demand is exploding. Physical constraints are hardening. The cost of wrong decisions is rising. Simulation-first operations are now cheaper than trial-and-error in the field.
• Competitive Dynamics
Hyperscalers own compute and distribution. Infra funds own land, power, and long-term contracts. Startup advantage lives in domain-specific models, clean data, and integration speed.
• Strategic Risks
- Model mis-specification can cause expensive real-world errors.
- Power and water scarcity can stall growth regardless of software quality.
- Regulatory approval cycles can drag GTM.
- Data quality and sensor drift can quietly degrade performance.
What Builders Should Notice
- Simulate before you build. A usable world model beats a bigger LLM in ops.
- Utilization is the business model. Price on saved capex and uptime.
- Distribution is offline. Win integrators, facilities, and utilities early.
- Trust is the moat. Validation, audits, and safe fallback modes are must-haves.
- Policy is a feature. Design for permits, reporting, and compliance from day one.
Buildloop reflection
“Better models matter. But better decisions pay the bills.”
Sources
- International Business Times — Built-world AI is the present and the future
- Global Tech Council — Are World Models the Future of AI?
- AIFOD — AI Realtime News — AI for Developing Countries
- LinkedIn — Why AI Infrastructure Is Becoming the New Asset Class
- Integrate — How to Invest in AI Infrastructure: Who Really Wins When Big Tech Goes All In
- YouTube — The Trillion-Dollar Friction: Why AI Infrastructure is Hitting a Wall
- Forbes — Artificial Intelligence: Poised To Transform The Massive Construction Industry