What Changed and Why It Matters
Banking is moving from AI as a helper to AI as an operator. The center of gravity is shifting from dashboards and chatbots to autonomous, policy-bound agents.
Two forces drive it. First, margin pressure and real-time risk require faster decisions. Second, legacy cores block scale. So banks are re-architecting around AI instead of layering it on top.
“Every bank will have to become AI-native. Most understand the imperative, yet rigid, decades-old infrastructure stands in the way.”
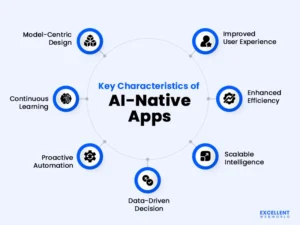
Zoom out and the pattern becomes obvious: AI-native beats AI-enabled when autonomy, guardrails, and trust are built into the core.
“AI-native banks will outperform AI-enabled banks, as the sustained advantage comes from redesigning the bank around AI, not layering AI tools.”
Here’s the part most people miss. Autonomy without a trust layer erodes credibility. Trust without autonomy erodes economics. The winners will balance both.
The Actual Move
Across the ecosystem, leaders are signaling the same pivot: rebuild for autonomy.
“Banks can’t just layer AI onto decades-old legacy systems – they need AI-native foundations.”
“Agentic systems now initiate, validate, and route transactions autonomously.”
“70% of banks are deploying AI agents.”
“As Agentic AI automates payments and lending, algorithms can amplify bias, threatening the entire credibility banking is built upon.”
“Banking that happens autonomously on your behalf within guardrails you control — no clicks, apps, or conscious effort required.”
“The autonomous enterprise connects finance, risk, customer engagement, workforce management, procurement, and operational processes.”
“Banks are already embedding AI into core workflows to help with fraud detection, risk monitoring, credit underwriting, customer service.”
What’s actually happening on the ground:
- Core redesign: Event-driven architectures replacing batch, so agents can act in real time.
- Agent orchestration: Policy- and role-based agents that trigger, decide, and settle.
- Trust layer: Identity, consent, explainability, and audit embedded at the transaction layer.
- Front-to-back automation: From underwriting to fraud to service resolution.
- Change in UX: Less screens, more intents. Banking shifts from clicks to outcomes.
The Why Behind the Move
Banks are optimizing for speed, safety, and continuous learning. Layering AI on legacy won’t get them there.
• Model
- From single LLM assistants to multi-agent systems executing tasks under policy.
- Data as a product: clean, labeled, real-time streams; retrieval over raw warehouses.
• Traction
- Early wins in fraud, collections, and service containment fund deeper core rebuilds.
- Autonomy converts opex savings into cycle-time advantages customers feel.
• Valuation / Funding
- AI-native narratives command premium multiples if tied to measurable risk-adjusted outcomes.
- Capex shifts: less branch/CX spend, more data infrastructure and control planes.
• Distribution
- Autonomy enables invisible banking in partner channels and ERP workflows.
- Trust and compliance become go-to-market features, not footnotes.
• Partnerships & Ecosystem Fit
- Core vendors (banking platforms, ERPs, cloud) provide the rails for safe autonomy.
- Co-innovation with regulators and risk teams reduces deployment friction.
• Timing
- The stack is ready: vector databases, event buses, policy engines, and eval suites.
- Competitive bar rises as pilots move from copilots to closed-loop execution.
• Competitive Dynamics
- AI-native banks will set new SLAs: instant decisions, proactive service, lower fees.
- Fintechs with modern cores can leapfrog incumbents stuck in batch.
• Strategic Risks
- Bias and drift can harden into systemic risk if audits are weak.
- Over-automation without human fallback invites brand and regulatory blowback.
- Model sprawl raises cost and control risks; platform thinking is mandatory.
What Builders Should Notice
- Trust is the moat. Build the consent, identity, and audit plane first.
- Don’t bolt AI on. Refactor flows around events, policies, and outcomes.
- Autonomy needs boundaries. Define fail-safes, handbacks, and explainability by design.
- Measure what matters. Track decision quality, time-to-resolution, and loss-adjusted ROI.
- Distribution shifts to embedded. Design for partner-triggered, invisible experiences.
Buildloop reflection
Autonomy without trust is a liability. Trust without autonomy is a tax.
Sources
- LinkedIn — Every bank will have to become AI-native. | Panagiotis Kriaris
- Bain & Company — What It Takes to Build the AI-Native Modern Bank
- Facebook (Huawei) — Banks can’t just layer AI onto decades-old legacy systems
- CodeNinja Consulting — The Trust Layer for AI-Native Banking and Payments
- nCino — Agentic AI in Banking: How Autonomous AI Is Transforming …
- Pure Storage Community — AI & Fintech: Can We Put Our Trust Into Autonomous …
- Backbase — AI-native banking: Why 92% of banks will fail at AI
- SAP — What Is the Autonomous Enterprise for Banking?
- Mercury — AI in banking: From automation to autonomous action